
What Are Production Overhead Costs?
Factory overhead is all production costs excluding direct materials and direct labor. These costs are necessary for the production process to run but cannot be directly traced to a specific product unit.
| Overhead Type | Example | Cost Characteristics |
|---|---|---|
| Auxiliary materials | Lubricant, glue, sandpaper, secondary packaging | Variables |
| Indirect labor | Supervisor, QC, maintenance technician, warehouse | Fixed / semi-variable |
| Factory utilities | Electricity, water, gas, air compressor | Semi-variable |
| Depreciation & rent | Machine depreciation, factory building rent | Still |
| Maintenance | Spare parts, regular service, emergency repairs | Variables |
| Others | Factory insurance, K3, production area cleanliness | Still |
NOTE. Production overhead costs are different from administrative or marketing overhead costs. Only costs incurred in the production area may be included in COGS..
Why Are Overhead Costs Difficult to Control?
There are several reasons why overhead is often a “stealth cost” in manufacturing companies:
- Spread across multiple departments. Electricity bills are recorded by general affairs, spare parts by purchasing, and supervisor salaries by HR. No one party sees the full picture.
- Recorded too late. Many companies only learn about their total overhead after the books are closed, when it's too late to take corrective action.
- Irrelevant allocation base. Apportioning overhead solely based on the number of units produced causes simple products to share the costs of complex products.
- Manual data entry in spreadsheets. Broken formulas, different file versions, and duplicate input make numbers difficult to trust.
CAUTION. Incorrect overhead allocation can lead you to set a selling price too low for a complex product. In the long run, the more of that product you sell, the greater the losses you incur without realizing it.
“You can't manage what you don't measure.”
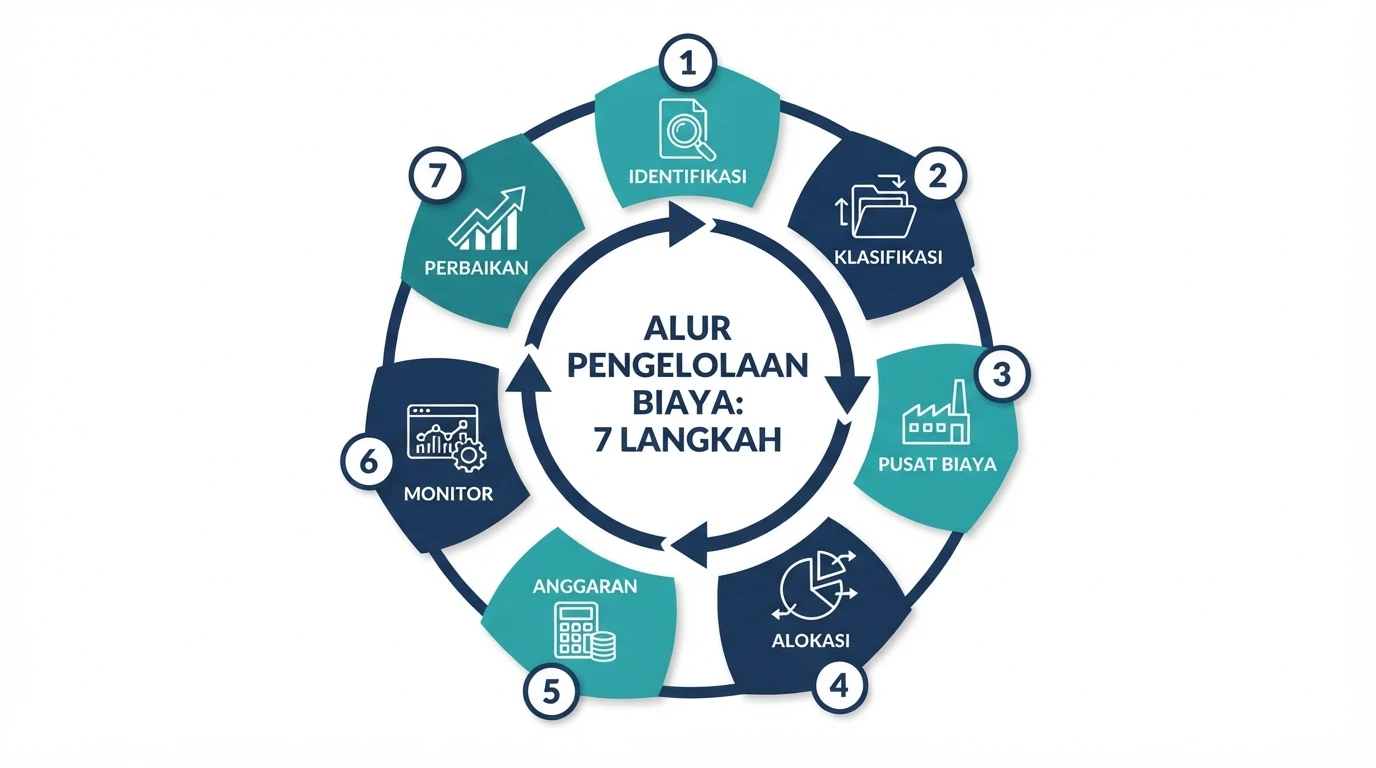
7 Steps to Control Production Overhead Costs More Efficiently
1. Identify All Overhead Sources
Start by mapping all cost items incurred in the production area over the past 6–12 months. Gather data from accounting, purchasing, HR, and maintenance. The goal is to create a comprehensive list so that no costs are overlooked.
2. Classify Fixed and Variable Costs
Separate fixed overhead (rent, depreciation) from variable overhead (machinery, auxiliary materials). Variable costs can be reduced through operational efficiency, while fixed costs can be controlled by increasing capacity utilization.
3. Form Cost Center and Work Center
BDivide the production floor into cost centers, such as cutting lines, assembly lines, painting, and packaging. Each work center has an hourly cost rate that includes electricity, machine depreciation, and indirect labor. This way, you know exactly which areas are the most "wasteful.".
4. Use the Right Allocation Basis
Choose an allocation basis that reflects the cost drivers. Electricity overhead is more appropriately allocated based on machine hours, while QC costs are based on the number of inspections. The Activity-Based Costing (ABC) approach helps produce a much more accurate overhead allocation than the single-rate method.
If you're not ready to implement full ABC, start with just two allocation bases: machine hours for machine-intensive lines and labor hours for labor-intensive lines. The results are already much better than using a single rate for the entire plant.
5. Prepare a Budget and Standard Overhead Rates
Establish a monthly overhead budget for each cost center, then calculate a predetermined overhead rate. This rate is used to consistently assign overhead to each production order throughout the period.
6. Monitor Variances in Real-Time
Compare actual overhead with applied overhead. Large variances indicate problems, such as frequent machine breakdowns, surging electricity usage, or idle capacity. The sooner variances are detected, the smaller the losses.
IMPORTANT FACTS
Overhead variances fall into two categories: spending variances (actual costs differ from budget) and volume variances (capacity used differs from plan). Both require different actions.
7. Make Continuous Improvements
Implement programs like preventative maintenance to reduce emergency repairs, energy audits to reduce electricity consumption, and tighter production scheduling to prevent idle machines. Evaluate the results monthly and use them as a reference for future budgets.
The Role of ERP in Production Cost Efficiency
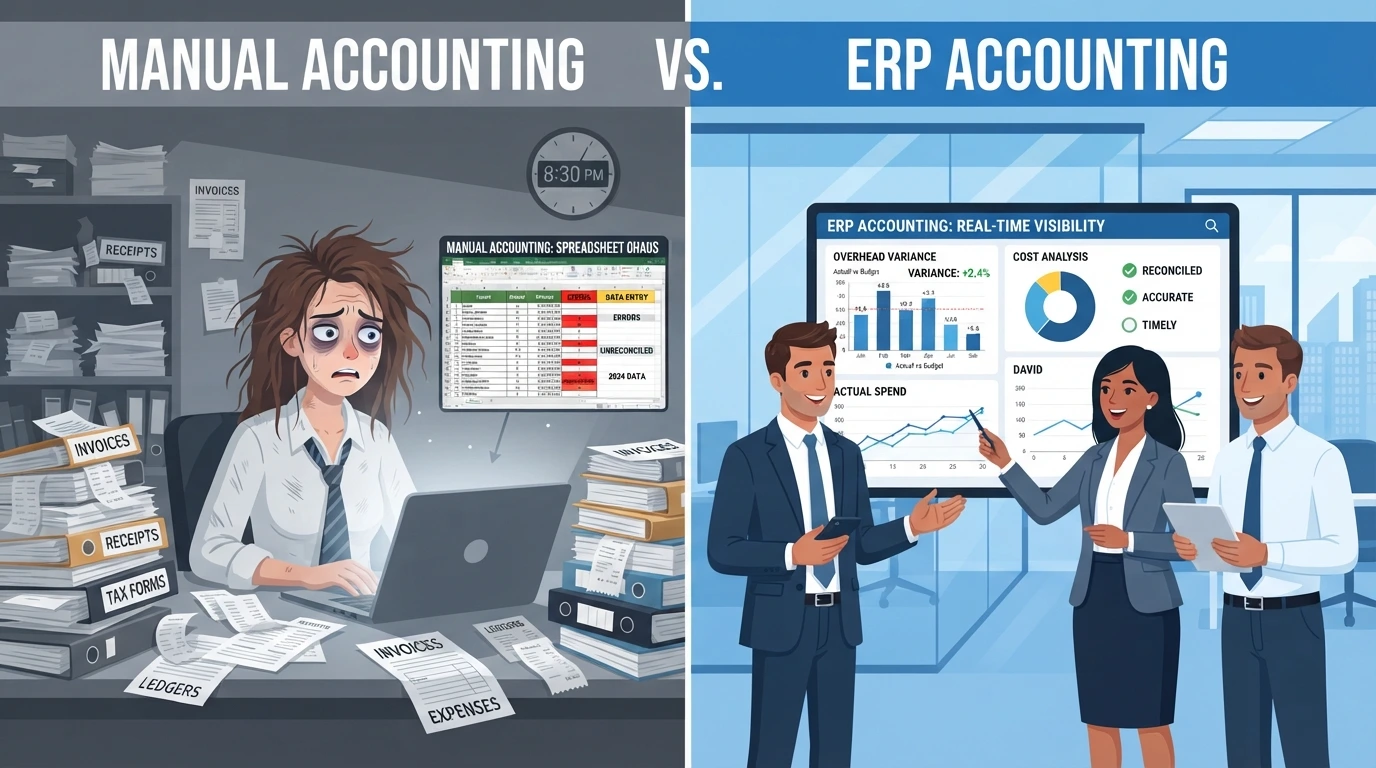
While all of the above steps can be done manually, they are tedious and prone to errors. This is where ERP software comes in. ERP integrates manufacturing, inventory, purchasing, accounting, HR, and maintenance modules into a single database, allowing every transaction to automatically flow into costing calculations.
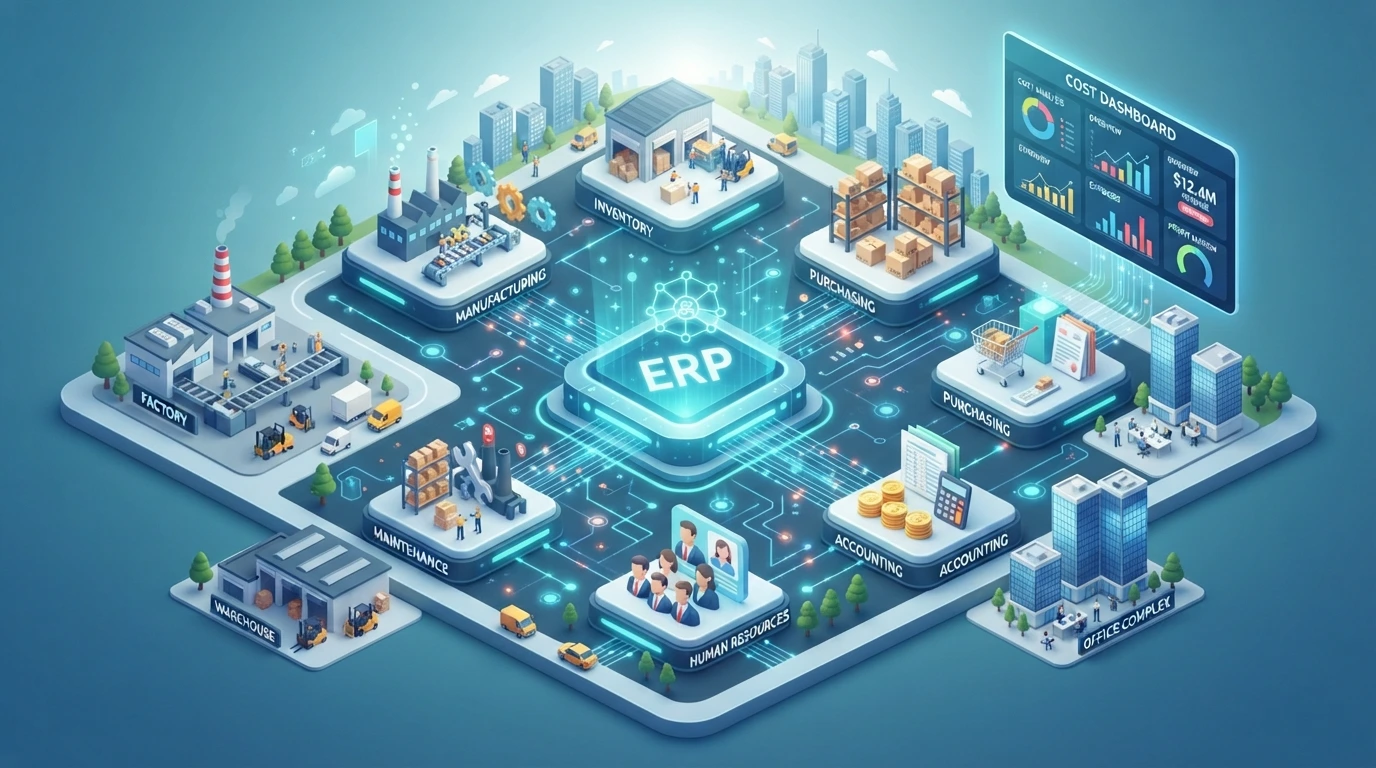
The following ERP capabilities have the greatest impact on overhead control:
- Work center with hourly rates. Each work order (manufacturing order) is automatically charged overhead based on the duration of machine use.
- Bill of Materials (BoM) and routing. Calculate standardized material requirements and processing times for each product.
- Analytic accounting. Every electricity bill, spare part purchase, or salary can be assigned to a specific cost center.
- Maintenance module. Schedules preventive maintenance and records repair costs per machine.
- Dashboard and variance reports. Management can view actual overhead versus budget at any time, without waiting for the books to close.
“ERP transforms overhead costs from mysterious numbers at the end of the month into actionable information every day..”
ATTENTION
ERP isn't an instant solution. Without clean master data (work centers, BoM, analytical accounts) and disciplined input from the production team, overhead calculations will remain inaccurate. Ensure implementation is accompanied by a consultant who understands manufacturing processes.
Common Mistakes to Avoid
- Using one overhead rate for the entire plant without considering process differences.
- Include head office administration costs in production overhead.
- Never update standard rates even though electricity prices or wages have increased.
- Ignoring idle capacity is actually a waste.
- Implementing ERP without user training on the production floor.
Conclusion: It's Time to Control Overhead with the Right System
Manufacturing overhead costs may not be as visible as raw materials, but their impact on COGS and margins is significant. By identifying cost sources, separating fixed and variable costs, establishing cost centers, selecting appropriate allocation bases, developing budgets, monitoring variances, and implementing continuous improvement, you can control overhead costs much more efficiently.
The key to success is integrated, real-time data. Manufacturing ERP provides that foundation, so every pricing, production, and machine investment decision is based on accurate numbers, not guesswork.
Want to implement an ERP that truly fits your factory's production processes? PT Fujicon Priangan Perdana is an IT consultant experienced in ERP implementation for various industries, from needs analysis, work center configuration and cost accounting, to post-go-live training and mentoring.
CONSULT YOUR ERP NEEDS NOW
Reduce overhead costs, improve COGS accuracy, and achieve healthier margins with Fujicon Priangan Perdana.
📱 WhatsApp: +62 811 2227 5222
🌐 Website: solusipintar.fujicon.id
Schedule a free consultation and find the best ERP solution for your manufacturing business.